Social Security announces 3.6% COLA for 2027, but Medicare premiums could eat into the $75 monthly raise
Social Security recipients will receive a 3.6% cost-of-living adjustment (COLA) in 2027, increasing average retirement benefits by about $75 a month. But with inflation reaching 3.7% in September and Medicare premiums for 2027 still awaiting official announcement, retirees may find that the increase provides less financial relief than expected.
The Social Security Administration (SSA) announced the adjustment on Oct. 14, with higher retirement, survivor and disability payments scheduled to begin in January. The increase will affect nearly 72 million Social Security beneficiaries, while approximately 7.3 million Supplemental Security Income (SSI) recipients will receive higher payments beginning Dec. 31, 2026.
Although the adjustment is intended to protect purchasing power, rising expenses for housing, food, transportation and health care could absorb much of the additional income. For retirees enrolled in Medicare, the final increase in their monthly checks will depend partly on changes to premiums and other deductions.
The average retiree will receive about $75 more per month
For retired workers, the 3.6% adjustment translates into an average monthly benefit increase of approximately $75. The SSA estimates that average retirement benefits will rise from $2,095 a month before the adjustment to $2,170 afterward.
The adjustment is automatic, meaning eligible beneficiaries do not need to submit a separate application to receive the increase.
That amounts to roughly $900 in additional benefits over a full year for someone receiving the average increase, assuming the benefit amount remains otherwise unchanged.
Individual increases will vary according to each recipient’s existing benefit. People receiving smaller monthly checks will generally receive smaller dollar increases, while those with larger benefits will receive more.
However, the $75 figure represents the average increase in Social Security retirement benefits, not a guaranteed increase for every recipient. The amount that ultimately reaches a beneficiary’s bank account may also be affected by Medicare premiums and other applicable deductions.
Inflation is running faster than the announced COLA
The 2027 adjustment comes as inflation continues to pressure household budgets. Consumer prices rose 3.7% in September compared with a year earlier, according to the latest Consumer Price Index report released on Oct. 14.
That rate exceeds the 3.6% Social Security adjustment for 2027, raising questions about whether the increase will be enough to maintain retirees’ purchasing power.
The comparison requires some caution because the COLA is based on the average inflation rate over the third quarter of 2026, rather than September’s annual inflation rate alone. Nevertheless, the latest figures illustrate the challenge facing beneficiaries as prices continue to rise.
Energy costs have been a particular concern amid geopolitical tensions and disruptions to global energy markets. Higher gasoline and transportation costs can affect retirees directly, while also contributing to expenses throughout the economy.
The Social Security COLA may not keep pace with rising prices, even as benefits increase to help retirees manage inflation.
One of the biggest uncertainties for retirees is how much Medicare premiums will rise in 2027. The federal government has not yet officially announced the new Medicare Part B premium, which covers physician services, outpatient care and other medical services.
Many beneficiaries have their Part B premiums deducted directly from their Social Security checks. That means a higher premium can reduce the amount of the COLA increase they actually keep.
The 2026 standard Part B premium is $202.90 a month. The 2026 Medicare Trustees Report projects that the standard premium could rise to $209.50 in 2027, an increase of $6.60 a month. That figure remains an estimate rather than the final announced premium.
If the projection proves accurate, a retiree receiving the average $75 monthly COLA increase would see approximately $6.60 of that increase offset by the higher standard Part B premium, leaving about $68.40 in additional monthly income before considering other changes or deductions.
The actual result will depend on the final premium, the beneficiary’s individual circumstances and any other changes to health care costs. Higher-income beneficiaries may pay more than the standard Part B premium, and changes in prescription drug coverage could create additional expenses.
The SSA says official Medicare information for 2027 will be available in late November. Until then, retirees should treat the projected premium as an estimate rather than a confirmed amount.
Medicare costs could make the real increase smaller
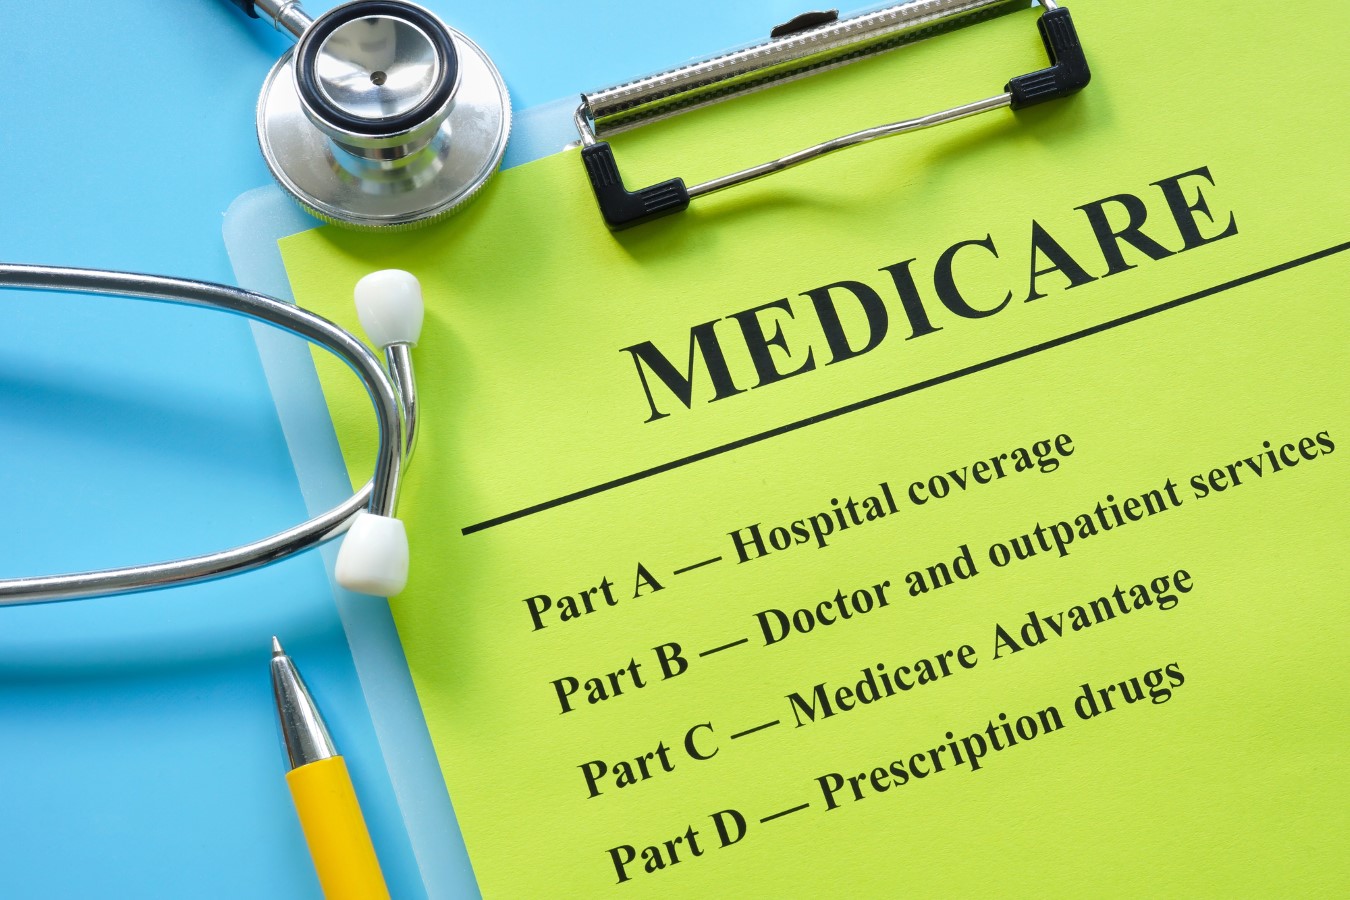
The potential impact extends beyond Part B premiums. Some retirees also pay Medicare Part D premiums for prescription drug coverage, along with deductibles, copayments and other out-of-pocket medical expenses.
Those costs can vary substantially depending on a person’s coverage, income and health care needs. As a result, two retirees receiving the same COLA increase may experience very different changes in their available income.
The National Committee to Preserve Social Security and Medicare has argued that rising health care costs can undermine the annual adjustment. The organization has supported changing the inflation measure used to calculate the COLA, saying the current formula does not adequately reflect the expenses older Americans face.
There is also an important distinction between a higher Medicare premium and a reduction in Social Security benefits. The increase in premiums generally reduces the net increase in a beneficiary’s payment; it does not automatically mean the recipient’s gross Social Security benefit will fall.
Federal rules also protect many existing beneficiaries from having their Part B premium increase reduce their Social Security payment in dollar terms, although those protections do not apply in every situation.
The COLA formula may not reflect retirees’ actual expenses
Social Security’s annual COLA is calculated using the Consumer Price Index for Urban Wage Earners and Clerical Workers, known as CPI-W. The SSA compares the average CPI-W for the third quarter of 2026 with the average for the third quarter of 2025.
The percentage increase between those periods determines the adjustment for 2027.
However, CPI-W reflects spending patterns for urban wage earners and clerical workers rather than focusing specifically on older Americans. Retirees may devote a larger share of their income to medical care, housing and other necessities than the households represented by the index.
That difference can be significant for people living on fixed incomes. Even if the official COLA matches the inflation measure used in the formula, an individual retiree’s personal expenses may rise faster.
Some advocates have called for the government to use the Consumer Price Index for the Elderly, or CPI-E, which is designed to better reflect the spending patterns of older Americans. Supporters argue that such a measure could produce adjustments that more closely match retirees’ costs, although the size of future increases would depend on how the index changes.
The 2027 increase is larger than last year’s adjustment
The 3.6% COLA is larger than the 2.8% adjustment for 2026 and marks the largest annual increase since the 8.7% adjustment in 2023.
The 2023 increase followed a period of unusually high inflation. Subsequent adjustments were smaller as inflation moderated, before rising again with the 2027 announcement.
The annual changes demonstrate how Social Security’s inflation protection responds to price movements rather than providing a fixed raise every year.
A larger COLA can offer meaningful relief, but it can also reflect a period when consumers have already experienced substantial price increases. For retirees, the key question is whether the additional benefits will cover the expenses they face in the coming year.
The COLA will also increase Supplemental Security Income payments for eligible older adults and people with disabilities who have limited income and resources.
The maximum federal monthly SSI payment standard for an eligible individual will rise from $994 in 2026 to $1,029 in 2027. For an eligible couple, the maximum federal payment standard will increase from $1,491 to $1,544.
Higher payments will begin on Dec. 31, 2026. Actual benefits can be lower depending on income and other eligibility factors, and some states provide additional supplements.
Because SSI recipients often have limited financial flexibility, changes in housing, food, energy and medical expenses can have an especially significant effect on their budgets.
Workers will face a higher Social Security taxable earnings cap
The SSA also announced an increase in the maximum amount of annual earnings subject to Social Security payroll taxes. The taxable maximum will rise from $184,500 in 2026 to $192,300 in 2027.
Workers earning above the current threshold will therefore have a larger portion of their income subject to Social Security payroll taxes next year. The change is separate from the COLA paid to beneficiaries.
The SSA also announced that the annual earnings limit for workers younger than full retirement age will increase to $25,560 in 2027. For people reaching full retirement age during 2027, the limit on earnings before the month they reach that age will rise to $67,920.
These earnings limits apply to beneficiaries who work while receiving Social Security before reaching full retirement age. Once a beneficiary reaches full retirement age, the earnings limit no longer applies.
Retirees can check their new benefits in late November
Beneficiaries will be able to review their individual COLA notices through their personal my Social Security accounts beginning in late November. The SSA said recipients who enroll in paperless notices by Nov. 18, 2026, can access their notices online before receiving a paper notice in the mail.
The notices will provide personalized information about new benefit amounts and applicable deductions. Recipients who do not enroll in paperless notices will receive their notices by mail in December.
The SSA also said that information about Medicare changes for 2027 will be available through Medicare, with the applicable premium information appearing in online Social Security accounts in late November.
For retirees planning their 2027 budgets, checking both the new Social Security benefit and the final Medicare premium will provide a clearer picture of how much additional income they can expect.
Trump’s tax law offers seniors a temporary deduction through 2028
President Donald Trump’s One Big Beautiful Bill introduced a new tax deduction of up to $6,000 for eligible taxpayers age 65 and older, providing another potential source of financial relief for retirees alongside the 2027 Social Security COLA. The deduction is available for tax years 2025 through 2028 and is in addition to the existing additional standard deduction for seniors. Eligible married couples filing jointly may qualify for a combined deduction of up to $12,000 if both spouses meet the requirements.
The deduction begins to phase out for taxpayers with modified adjusted gross income above $75,000, or $150,000 for married couples filing jointly. It can reduce taxable income and potentially lower the federal income taxes owed on Social Security benefits, but it does not directly eliminate taxes on those benefits. The provision is temporary and is scheduled to expire after 2028, meaning retirees should not assume the tax relief will continue indefinitely under current law.
For retirees, the deduction and the COLA serve different purposes. The COLA increases monthly benefits, while the tax deduction may reduce annual federal income tax liability for eligible taxpayers. Neither guarantees that retirees will keep pace with rising living expenses, particularly if Medicare premiums and other essential costs increase.
The 2027 COLA offers relief, but retirees face lingering uncertainty
The 3.6% adjustment will increase Social Security payments for millions of Americans, but the final financial benefit will depend on inflation and other household expenses.
The latest 3.7% annual inflation reading suggests that prices remain a concern, while the pending Medicare premium announcement leaves uncertainty about how much of the average $75 increase retirees will retain.
The preliminary estimate for the standard Part B premium points to a $6.60 monthly increase, which would offset part of the COLA for many beneficiaries. But that amount has not yet been finalized, and additional changes to prescription drug coverage and other expenses could further affect household budgets.
Trump’s One Big Beautiful Bill offers another potential source of relief through its $6,000 senior tax deduction, but that provision is scheduled to expire after 2028. The deduction may reduce federal income taxes for eligible older Americans, yet it does not guarantee that Social Security benefits will be tax-free or that retirees’ expenses will remain affordable.
For now, beneficiaries can prepare by reviewing their Social Security notices, accounting for potential Medicare cost increases and checking their eligibility for the senior tax deduction. The 2027 COLA will provide additional income, but the amount retirees ultimately retain; and whether that money keeps pace with the cost of retirement; will matter more than the headline percentage.
Like Financial Freedom Countdown content? Be sure to follow us!
Did you find this article helpful? We’d love to hear your thoughts! Leave a comment with the box on the left-hand side of the screen and share your thoughts.
Also, do you want to stay up-to-date on our latest content?
1. Follow us by clicking the [+ Follow] button above,
2. Give the article a Thumbs Up on the top-left side of the screen.
3. And lastly, if you think this information would benefit your friends and family, don’t hesitate to share it with them!
John Dealbreuin came from a third world country to the US with only $1,000 not knowing anyone; guided by an immigrant dream. In 12 years, he achieved his retirement number.
He started Financial Freedom Countdown to help everyone think differently about their financial challenges and live their best lives. John resides in the San Francisco Bay Area enjoying nature trails and weight training.
Here are his recommended tools
Personal Capital: This is a free tool John uses to track his net worth on a regular basis and as a retirement planner. It also alerts him wrt hidden fees and has a budget tracker included.
Platforms like Yieldstreet provide investment options in art, legal, real estate, structured notes, venture capital, etc. They also have fixed-income portfolios spread across multiple asset classes with a single investment with low minimums of $10,000.