Bernie Sanders targets $2,400 Social Security boost as Democrats take control of Congress
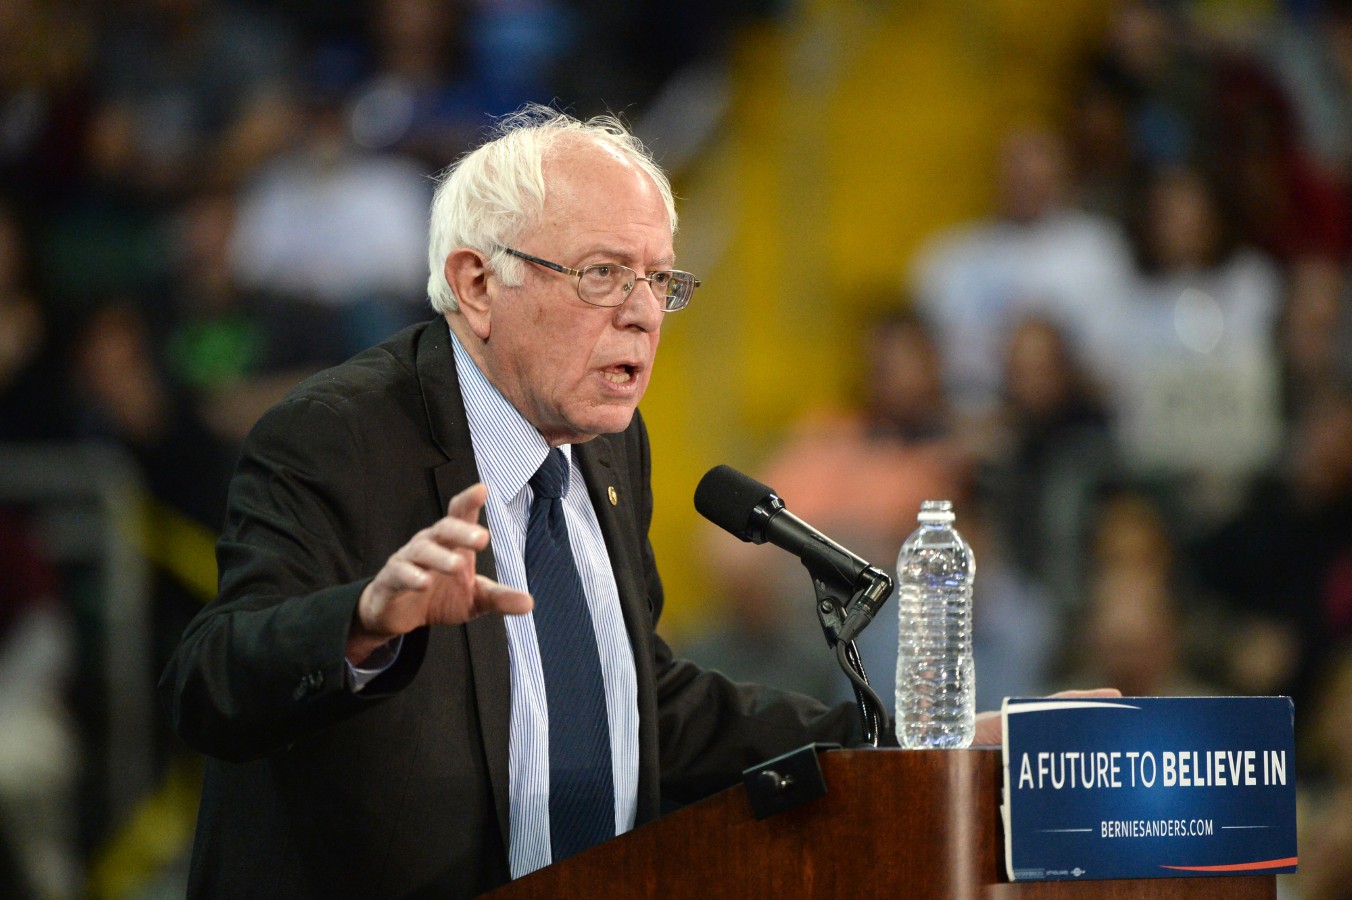
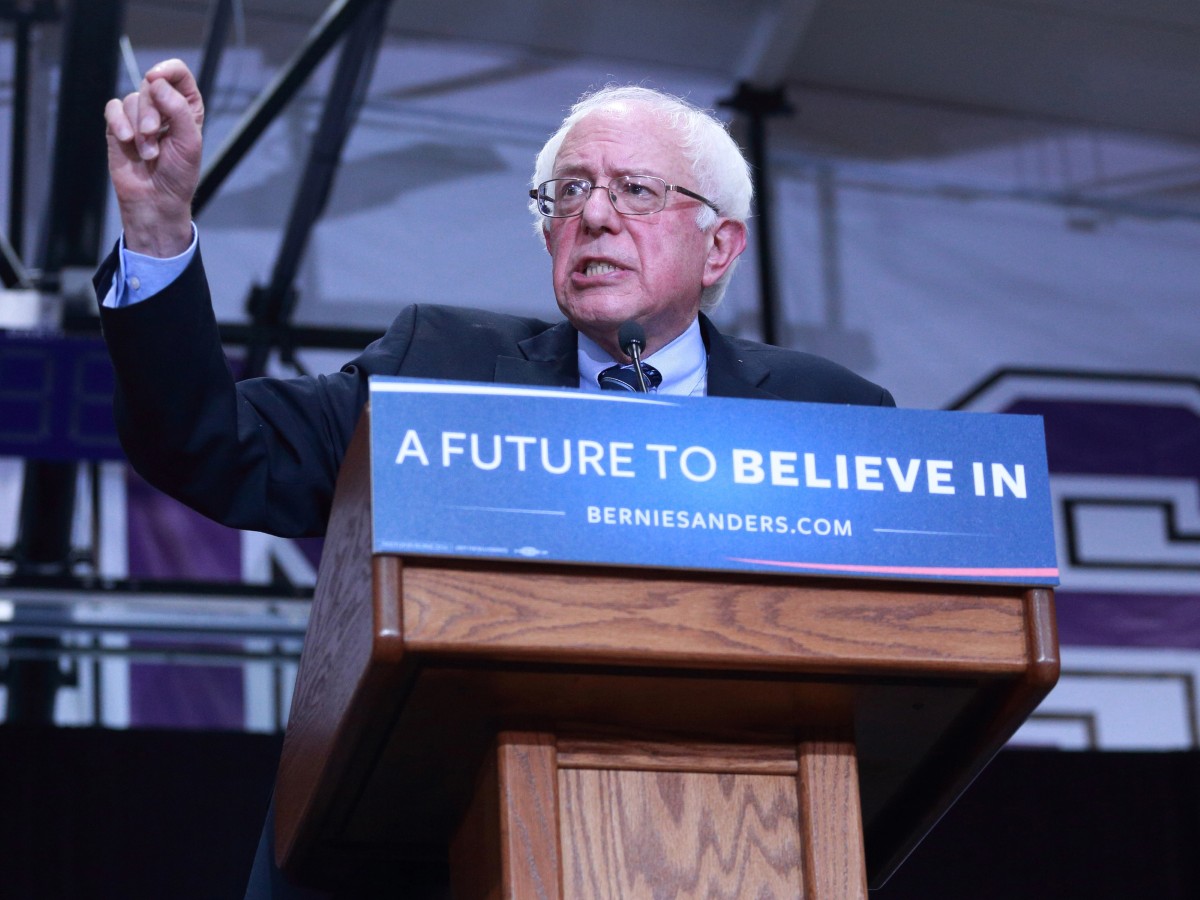
Sen. Bernie Sanders is putting Social Security expansion at the center of his agenda following Democrats’ sweeping victories in the November 2026 midterm elections. With Republicans set to lose control of both chambers of Congress, the Vermont independent sees an opportunity to revive legislation that would increase Social Security benefits by at least $2,400 annually while addressing the program’s long-term funding problems.
In a November 7 post on X, Sanders outlined his priorities as the next chair of the Senate Social Security Subcommittee, arguing that higher-income Americans should contribute more toward the retirement program.
“As the next chair of the Social Security Subcommittee, a top priority will be to expand Social Security benefits by at least $2,400 a year & extend Social Security’s solvency for generations.
How? By scrapping the cap & demanding that the wealthy pay their fair share of taxes.”
The proposal comes as Social Security faces a growing financing challenge, with the latest trustees’ projections pointing to a depletion of the retirement trust fund’s reserves in 2032. Sanders wants to address that problem by collecting payroll taxes on earnings above the current taxable maximum, rather than reducing benefits or increasing taxes on most American workers.
Sanders sees a new opportunity after Democratic election victories
The November 3 midterm elections dramatically changed the political landscape in Washington. Democrats won control of both the House of Representatives and the Senate, ending unified Republican control and setting up a divided government when the new Congress begins in January 2027.
The victories included Democratic gains in traditionally competitive and Republican-leaning states. Democrats flipped at least seven Senate seats and made substantial gains in the House, while also winning several governorships and other statewide offices.
The results give Democrats control over congressional committees, including those responsible for Social Security legislation and oversight. That could allow Sanders and other lawmakers who favor expanding retirement benefits to hold hearings, advance legislation and challenge proposals that would reduce benefits.
For Sanders, the election results represent more than a change in congressional leadership. They offer an opportunity to turn Social Security expansion into a central part of the Democratic legislative agenda.
Sanders is positioned to lead the Social Security Subcommittee
Sanders currently serves as the ranking member of the Senate Finance Committee’s Subcommittee on Social Security, Pensions, and Family Policy. Republicans have controlled the Senate during the 119th Congress, leaving Sen. Chuck Grassley as the subcommittee chairman.
With Democrats winning the Senate majority, Sanders expects to become the next chair when the 120th Congress convenes in January 2027.
The position would give him a more influential role in shaping the committee’s legislative priorities, organizing hearings and examining proposals affecting retirement benefits, pensions and Social Security financing.
However, the leadership change is not yet formally complete. The new Senate majority must establish its committee assignments and leadership positions.
Sanders’ potential chairmanship is particularly significant because Social Security reform has been a longstanding priority for him. He has repeatedly argued that the program’s financial problems should be addressed by collecting more revenue from wealthy Americans rather than asking retirees and middle-income workers to accept benefit reductions.
Social Security faces a 2032 funding deadline

The financial outlook for Social Security provides an important backdrop to Sanders’ proposal.
According to the 2026 Social Security Trustees Report, the Old-Age and Survivors Insurance (OASI) Trust Fund, which finances retirement and survivor benefits, is projected to deplete its reserves in the fourth quarter of 2032.
At that point, continuing payroll tax revenue and other income would be sufficient to cover only 78% of scheduled benefits if Congress does not change the law.
That does not mean Social Security would stop paying benefits altogether. Workers and employers would continue contributing payroll taxes, but the money coming into the program would not be enough to cover the full amount currently promised.
The combined Social Security trust funds, which include retirement and disability insurance, have a later projected depletion date of 2034, when approximately 83% of scheduled benefits would remain payable.
The distinction matters because Sanders’ proposal addresses the program’s broader financing structure, while the 2032 date specifically concerns retirement and survivor benefits.
The trustees have also warned that Social Security’s costs are expected to exceed its income throughout the 75-year projection period. That makes congressional action increasingly important, particularly for younger workers who could otherwise face lower benefits when they retire.
Scrapping the payroll tax cap is central to Sanders’ plan

Sanders’ preferred solution involves changing the maximum amount of annual earnings subject to Social Security payroll taxes.
Under current law, workers pay a 6.2% Social Security payroll tax on wages up to an annual limit. Employers contribute another 6.2%, bringing the combined rate to 12.4%.
For 2026, the taxable maximum is $184,500. Earnings above that amount are not subject to Social Security payroll taxes, although they remain subject to Medicare taxes.
This means someone earning $184,500 and someone earning $1 million annually pay the same maximum amount in employee Social Security payroll taxes.
Sanders argues that this structure disproportionately benefits high-income Americans because a smaller share of their total earnings is subject to the tax.
His proposal would change the treatment of earnings above the current taxable maximum, with the objective of requiring wealthy workers to contribute more toward Social Security.
Sanders is not proposing a general increase in the Social Security payroll tax rate for all workers. His political argument is that additional revenue should come primarily from higher-income Americans.
The proposed $2,400 annual benefit increase could help retirees
Sanders is not simply proposing to collect more payroll taxes. He also wants to increase the benefits paid to retirees, people with disabilities and other Social Security recipients.
His proposed $2,400 annual increase translates to approximately $200 per month.
That could provide meaningful additional income for retirees who depend heavily on Social Security to cover housing, groceries, utilities and medical expenses.
The increase is particularly relevant as retirees continue to face higher living costs. Social Security’s annual cost-of-living adjustments are calculated using the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W), which does not specifically track the spending patterns of older Americans.
Sanders has also advocated using the Consumer Price Index for the Elderly (CPI-E) to calculate annual adjustments. Older households often spend a larger share of their income on health care and housing, making the choice of inflation measure important.
His broader objective is to strengthen Social Security’s purchasing power while ensuring that the program can continue paying full benefits over the long term.
Social Security Expansion Act provides the legislative blueprint
Sanders has already introduced legislation that closely matches the priorities outlined in his November 7 post.
On February 27, 2025, he introduced the Social Security Expansion Act (S. 770) with support from several Democratic senators, including Elizabeth Warren of Massachusetts, Jeff Merkley of Oregon, Peter Welch of Vermont and Alex Padilla of California.
The House companion legislation, H.R. 1700, was introduced by Rep. Val Hoyle of Oregon.
The legislation seeks to expand benefits while addressing Social Security’s long-term financing shortfall. Its provisions include several important changes:
Across-the-board benefit increases: The bill modifies the Social Security benefit formula to increase payments for beneficiaries.
A $2,400 annual benefit expansion: Sanders’ office describes the proposal as providing an additional $200 per month.
A different inflation measure: The legislation replaces CPI-W with CPI-E for calculating future cost-of-living adjustments.
Higher minimum benefits: It increases the minimum benefit for qualifying lifetime low-income workers based on their years in the workforce.
Expanded benefits for children: It extends eligibility for certain children of disabled or deceased workers who remain full-time students, potentially through age 22.
Additional tax revenue: It changes the payroll tax treatment of earnings above the existing taxable maximum and includes additional taxation of investment income.
The investment-income provision is particularly noteworthy. The bill proposes increasing the existing 3.8% net investment income tax to 16.2% and broadening its application to certain active business income. A portion of the resulting revenue would support the Social Security trust fund.
The legislation was referred to the Senate Finance Committee after its introduction and has not become law.
Sanders’ office has argued that the bill would fully fund Social Security for 75 years while increasing benefits. However, the precise actuarial impact of the 2025 version should be distinguished from the Social Security Administration’s analysis of earlier versions of the legislation.
Supporters argue that wealthy Americans should contribute more
Supporters of eliminating the payroll tax cap argue that Social Security’s funding structure has not kept pace with changes in income distribution.
A larger share of total wage income now goes to high earners, while the amount of earnings subject to Social Security taxes remains limited by the annual taxable maximum.
The Economic Policy Institute has argued that eliminating the cap could address a substantial portion of Social Security’s projected funding shortfall.
In a December 2025 analysis, the organization estimated that scrapping the cap without providing additional benefits for the newly taxed earnings could eliminate nearly three-fourths of the program’s projected long-term shortfall.
Supporters also argue that the proposal would protect workers who have spent decades contributing to Social Security but could otherwise face benefit reductions if Congress fails to act.
The Economic Policy Institute has made another interesting argument: higher earners could also benefit from avoiding across-the-board Social Security benefit cuts.
Its analysis estimated that 70% of workers aged 32 to 66 who earned above the taxable maximum in 2024 would lose more through potential benefit reductions than they would pay in additional taxes if the cap were eliminated.
For Sanders and other supporters, the central argument is that Social Security is a broad social insurance program, and its long-term stability should not depend on reducing benefits for ordinary workers.
Critics question whether higher Social Security taxes would earn higher benefits
One of the biggest objections to Sanders’ proposal is not simply that it would increase taxes on wealthy Americans. It is that those paying additional Social Security payroll taxes on earnings above $250,000 would not receive corresponding individual benefit credits for those additional contributions.
Under the Social Security Expansion Act, Sanders proposes taxing earnings above $250,000 while retaining the existing taxable maximum for calculating individual benefits. This means high earners could pay additional Social Security taxes without having those newly taxed earnings proportionately increase their future retirement checks.
The distinction matters because Social Security traditionally links contributions to benefits. The same taxable earnings base generally determines how much workers contribute and how much of their earnings count toward their eventual retirement benefits.
Sanders’ legislation takes a different approach. Rather than providing higher individual benefits based on all newly taxed earnings, it directs additional revenue toward improving the program’s overall finances while increasing benefits through separate provisions that apply more broadly.
Critics argue that this weakens the connection between what individuals pay into Social Security and what they receive in return. They also question whether it is fair to impose additional payroll taxes without providing corresponding retirement benefits.
The Congressional Research Service has identified this as a central consideration in proposals to raise or eliminate the taxable earnings cap. Maintaining a lower benefit calculation base while expanding the contribution base can improve Social Security’s long-term finances, but it also changes the traditional relationship between contributions and benefits.
Supporters, meanwhile, argue that Social Security is a social insurance program, not an individual retirement investment account. They contend that higher earners can reasonably contribute more to preserve benefits for millions of Americans, even if their own retirement payments do not increase proportionately.
The disagreement ultimately reflects two different views of Social Security: whether it should primarily reward individual contributions or operate more broadly as a system of income protection and redistribution.
Democratic victories could revive Social Security expansion, but political obstacles remain
Democrats’ election victories could give Sanders a stronger platform to advance his legislation.
With control of the Senate and House, Democrats will have the ability to determine committee leadership, schedule hearings and decide which legislation receives attention.
The election results also strengthened progressive Democrats who have campaigned on affordability, retirement security and higher taxes on wealthy Americans.
However, a congressional majority does not automatically guarantee passage of the Social Security Expansion Act.
Democrats have a diverse coalition, ranging from progressives who support expanding benefits to moderates who may be more cautious about substantial payroll tax increases.
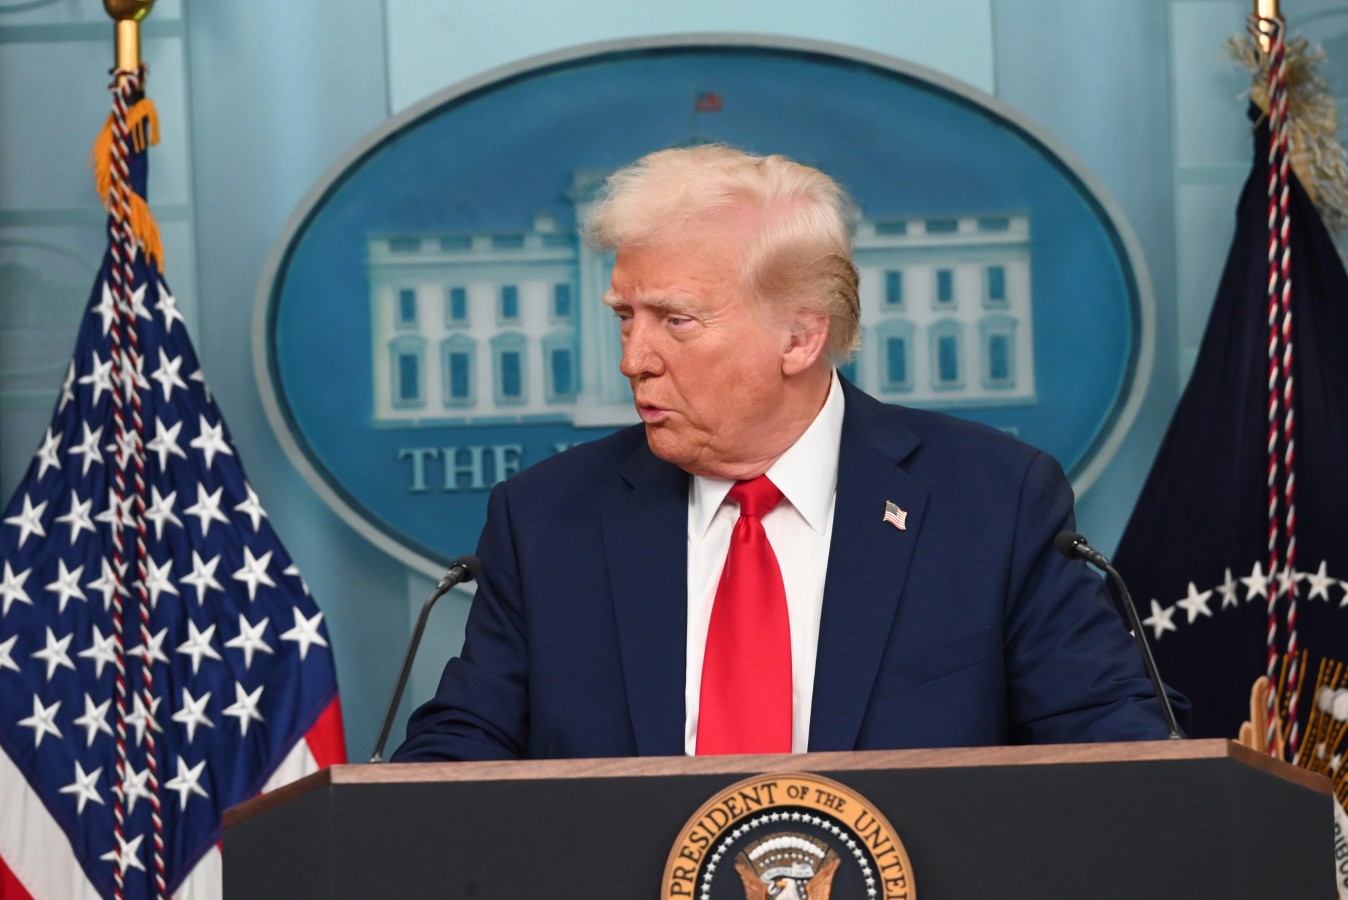
The party will also need to contend with President Donald Trump, who will remain in office even after Republicans lose congressional control. The president can veto legislation, meaning Democrats would generally need Republican support to overcome a veto unless they pursue a different legislative strategy.
Social Security reform could therefore become an important test of whether the Democratic majority can unite around a common economic agenda.
There is also a broader political question: Will Democrats prioritize expanding benefits, protecting existing payments or negotiating a bipartisan financing agreement?
Sanders has made clear that he favors expansion rather than benefit reductions. Whether the rest of his party adopts that position remains to be seen.
The next Congress faces a debate over who pays for Social Security’s future
Sanders’ anticipated leadership role puts him in a stronger position to make Social Security expansion a priority in the next Congress. His 2025 Social Security Expansion Act provides an existing legislative framework, while the latest trustees’ projections give lawmakers another reason to examine the program’s finances.
But the proposal raises a fundamental question about the future of Social Security: Should wealthy Americans pay payroll taxes on more of their earnings even if those additional contributions do not translate into proportionately higher individual retirement benefits?
Sanders argues that higher earners should contribute more to protect the program, while beneficiaries should receive at least $2,400 more annually. Critics counter that taxing additional earnings without providing corresponding benefit credits weakens the traditional relationship between contributions and benefits.
That distinction is central to understanding the legislation. Sanders is not simply proposing to expand the existing Social Security system by making high earners pay more and receive larger retirement checks. He is proposing a broader redistribution of the program’s financing, with additional revenue helping fund higher benefits across the beneficiary population.
Whether Democrats can unite behind that approach remains to be seen. They must also address the political and legislative obstacles to passing a major Social Security overhaul, particularly with President Donald Trump remaining in the White House.
With the retirement trust fund projected to deplete its reserves in 2032, the next Congress will face increasing pressure to act. The debate will not just be about how much money Social Security needs, but also about who should shoulder the additional costs and whether the benefits received should reflect the taxes paid.
The outcome could have implications beyond the immediate legislative session. Social Security is a major concern for retirees, younger workers and families planning for retirement. How Democrats address the balance between higher contributions, benefit expansion and fairness could become an important part of their economic message heading into the 2028 elections.
Like Financial Freedom Countdown content? Be sure to follow us!
Did you find this article helpful? We’d love to hear your thoughts! Leave a comment with the box on the left-hand side of the screen and share your thoughts.
Also, do you want to stay up-to-date on our latest content?
1. Follow us by clicking the [+ Follow] button above,
2. Give the article a Thumbs Up on the top-left side of the screen.
3. And lastly, if you think this information would benefit your friends and family, don’t hesitate to share it with them!
John Dealbreuin came from a third world country to the US with only $1,000 not knowing anyone; guided by an immigrant dream. In 12 years, he achieved his retirement number.
He started Financial Freedom Countdown to help everyone think differently about their financial challenges and live their best lives. John resides in the San Francisco Bay Area enjoying nature trails and weight training.
Here are his recommended tools
Personal Capital: This is a free tool John uses to track his net worth on a regular basis and as a retirement planner. It also alerts him wrt hidden fees and has a budget tracker included.
Platforms like Yieldstreet provide investment options in art, legal, real estate, structured notes, venture capital, etc. They also have fixed-income portfolios spread across multiple asset classes with a single investment with low minimums of $10,000.