Trump claims prices are falling, but Gallup poll shows voters across generations facing deep anxiety
With the midterm elections approaching, economic conditions and personal finance are taking center stage in national debate. As households across the country navigate stubborn inflationary pressures and rising interest rates, public sentiment reflects a mixture of frustration and uncertainty.
Economic pressure is mounting across the U.S. as voters prepare to head to the polls. Heading into the midterms, persistent inflation remains a primary concern for households struggling to manage everyday expenses.
Despite signs of moderation in certain macroeconomic indicators, consumer costs remain elevated compared to pre-inflationary baselines. As a result, kitchen-table economic issues have emerged as a dominant influence on voter sentiment.
For most Americans, the impact of inflation is felt most directly in recurring, non-negotiable monthly expenses. Everyday necessities; ranging from food to transportation and housing; have seen continuous upward pressure on pricing.
As highlighted in recent financial reporting, “The price of eating out, filling a gas tank and buying a house keeps rising.” These compounding increases make it difficult for working families to maintain standard living budgets without adjusting spending habits or relying more heavily on credit.
The Federal Reserve acts as borrowing costs climb higher
To counter ongoing inflation, the Federal Reserve has maintained a restrictive monetary policy stance, taking action to cool down demand across the economy. However, higher benchmark interest rates create a secondary challenge for consumers looking to borrow.
“The Fed raised rates to try to tamp down inflation, but that will make borrowing more expensive too.” The ripple effects are visible across consumer credit markets, where mortgage rates have climbed toward 6.95%, adding significant friction to auto loans, personal credit lines, and home purchasing.
Political rhetoric clashes with grocery store reality
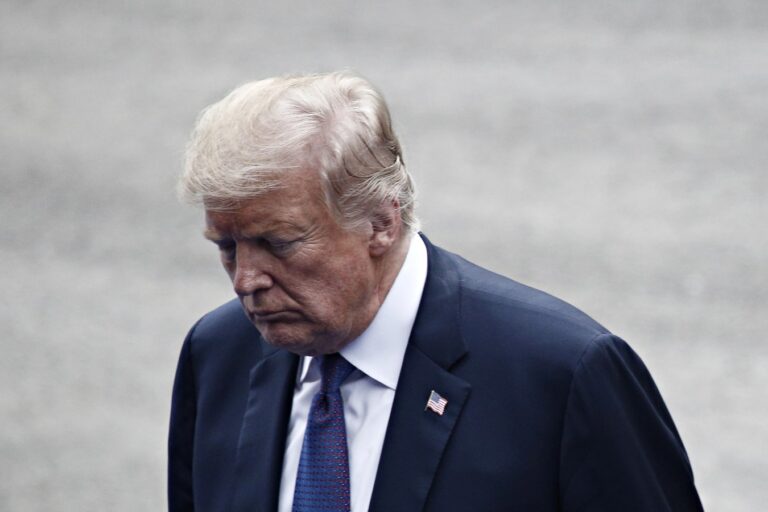
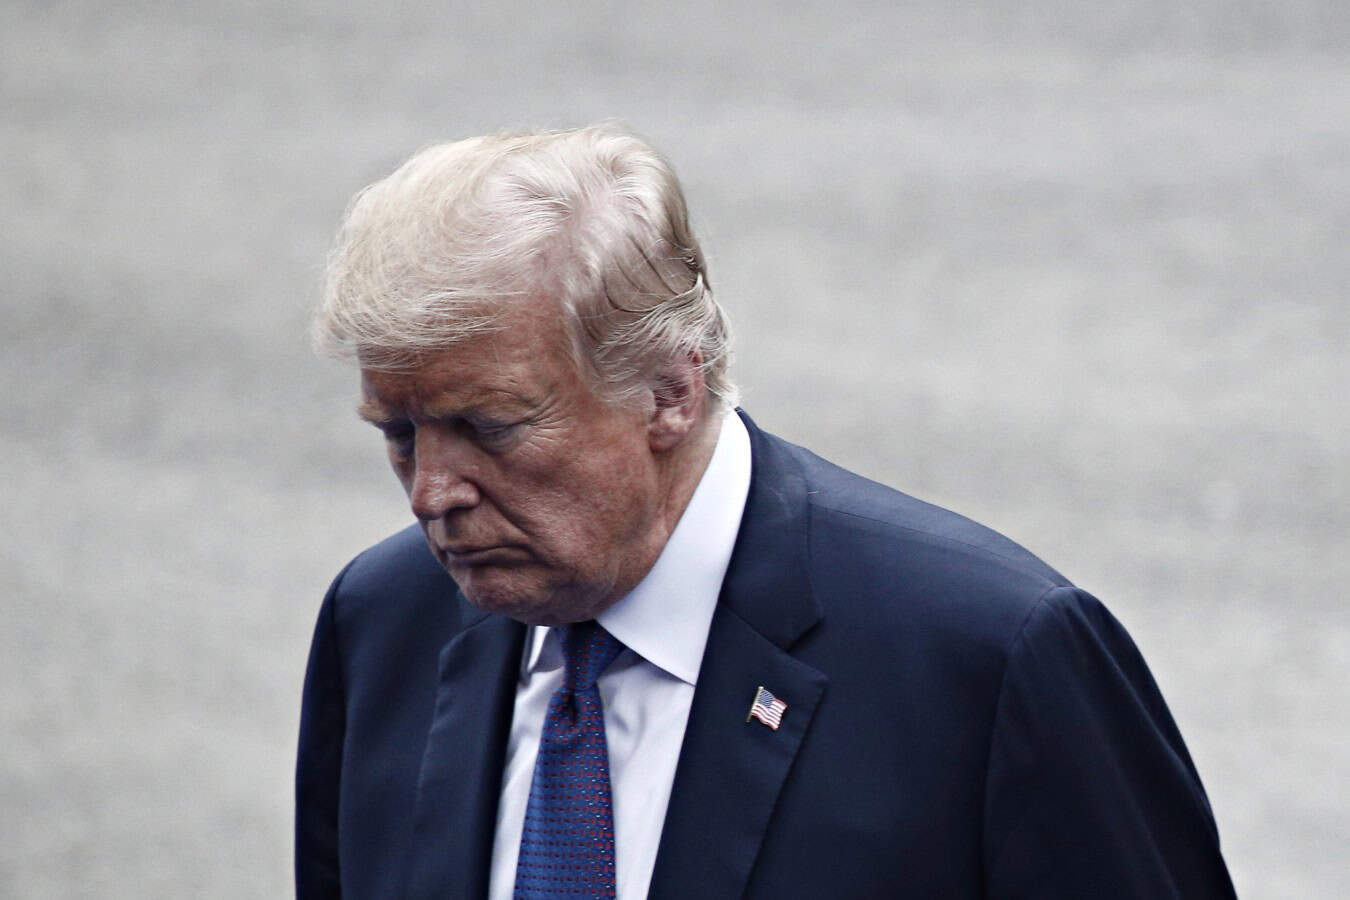
As political figures campaign across the nation, messaging around the economy has drawn intense scrutiny. Political statements frequently attempt to reframe the state of inflation to influence voter perception.
In particular, political commentary surrounding claims that “almost every item” is getting cheaper has encountered skepticism from voters who face high checkout totals. Economists point out that even when the inflation rate slows, price levels generally remain high rather than returning to lower previous levels.
The gap between optimistic political narratives and actual consumer experience highlights a broader disconnect in public perception. While official statistics may show a deceleration in the rate of price growth, consumers experience cumulative price levels at the grocery store and gas pump.
This tension creates political vulnerability for incumbents and opportunities for challengers. Voters frequently judge the strength of the economy based on immediate purchasing power rather than high-level economic indicators or political assurances.
Gallup data highlights a widespread deficit in financial confidence
Beyond macroeconomic metrics, survey data reveals how economic pressures impact personal financial confidence across age groups. According to the Edward Jones/Gallup 2026 Money and Meaning: Understanding Financial Fulfillment study, confidence in managing day-to-day finances varies significantly by age.
The poll found that only 25% of Gen Z adults and 31% of Millennials in the U.S. report having a great deal of confidence in their ability to manage current financial needs. By comparison, 38% of Gen X adults and 54% of Baby Boomers express high confidence in managing current finances.
Younger generations face distinct pressures on current expenses
For younger Americans, financial stress is tied directly to cash flow, housing affordability, and income growth. With entry-level wages struggling to keep pace with housing and consumer costs, younger adults report higher levels of day-to-day financial anxiety.
In the U.S., more than six in 10 Gen Z and Millennial adults say that increasing household income is a high priority. Furthermore, 41% of Gen Z adults prioritize saving for a home, compared to just 2% of Baby Boomers, reflecting how life-stage financial goals align with changing economic realities.
Retirement worries loom large for Gen X workers
While older generations report higher confidence in handling immediate finances, uncertainty regarding future financial security remains widespread. Gen X adults; the cohort currently approaching retirement age; express notable worry about long-term savings.
In the U.S., only 26% of Gen X adults express a great deal of confidence in managing their future financial needs. Although 59% of U.S. Gen Xers report having a financial plan for retirement, 39% worry about whether their current and future savings will last through their retirement years.
Despite generational differences in financial confidence and life-stage goals, Americans across all age brackets share core economic values. Financial security remains the primary goal regardless of age.
Across all generations in the U.S., between 67% and 77% of adults identify being financially secure as a top priority. Additionally, every age group consistently highlights “having income for a healthy lifestyle” as a leading personal finance objective.
A challenging economic horizon for policymakers and voters
As the midterms approach, the combination of high living costs, rising borrowing rates, and mixed financial confidence creates a complex landscape. Voters are tasked with evaluating political platforms against their personal financial situations.
Whether policymakers can address persistent inflation without triggering broader economic instability remains a central question. In the meantime, households across the country continue to adjust to elevated prices while planning for an uncertain financial future.
Like Financial Freedom Countdown content? Be sure to follow us!
14 essential strategies to maximize your Social Security and avoid costly mistakes
Social Security is a vital lifeline for many seniors, providing crucial income support during retirement. With inflation at its highest in four decades, Social Security’s inflation-adjusted benefits offer protection against rising costs.
Rising interest rates have disrupted many retirement portfolios, causing bond fund values to plummet. In this volatile financial landscape, Social Security can stabilize a typical stock-bond retirement portfolio. By implementing smart strategies, retirees can maximize their Social Security benefits and ensure a more secure financial future.
14 Essential Strategies to Maximize Your Social Security and Avoid Costly Mistakes
11 reasons you should claim Social Security early
Deciding when to claim Social Security is often about maximizing your benefit. Financial planners usually advise delaying your claim for as long as possible to secure the highest monthly payment. Your benefit is based on your lifetime earnings, with a full payout available at your full retirement age (FRA), which is currently between 66 and 67 depending on your birth year. Claiming before FRA results in a permanent reduction in your monthly benefit, while waiting beyond FRA leads to a permanent increase. However, the decision isn’t solely about maximizing the monthly check. Personal factors such as health, family circumstances, and financial needs can play a significant role in determining the right time to claim.
11 Reasons You Should Claim Social Security Early
Did you find this article helpful? We’d love to hear your thoughts! Leave a comment with the box on the left-hand side of the screen and share your thoughts.
Also, do you want to stay up-to-date on our latest content?
1. Follow us by clicking the [+ Follow] button above,
2. Give the article a Thumbs Up on the top-left side of the screen.
3. And lastly, if you think this information would benefit your friends and family, don’t hesitate to share it with them!
John Dealbreuin came from a third world country to the US with only $1,000 not knowing anyone; guided by an immigrant dream. In 12 years, he achieved his retirement number.
He started Financial Freedom Countdown to help everyone think differently about their financial challenges and live their best lives. John resides in the San Francisco Bay Area enjoying nature trails and weight training.
Here are his recommended tools
Personal Capital: This is a free tool John uses to track his net worth on a regular basis and as a retirement planner. It also alerts him wrt hidden fees and has a budget tracker included.
Platforms like Yieldstreet provide investment options in art, legal, real estate, structured notes, venture capital, etc. They also have fixed-income portfolios spread across multiple asset classes with a single investment with low minimums of $10,000.